
Gratuity Calculation India 2026 – Exact Formula and the 4 Year 8 Month Rule
By Mukesh | MoneyOra | Last verified 12 October 2026
Gratuity calculation India 2026 follows one formula that every working Indian should know. This article on gratuity calculation India 2026 gives you the formula with five real rupee examples covering different salaries and tenures and explains the 4 year 8 month rule that most HR teams apply wrongly. You also get the full claim process and a tax exemption guide.
If you are resigning before five years or have just crossed five years this gratuity calculation India 2026 guide is the one article you need before you file your claim.
What is gratuity and which people does the law cover?
Gratuity is a one‑time lump sum payment that an employer gives when you leave after years of work. The rules for gratuity calculation India 2026 come from the Payment of Gratuity Act of 1972. Gratuity is not a bonus. Is not part of your normal salary. The Payment of Gratuity Act of 1972 is the law that protects private sector employees in India as confirmed on labour.gov.in
The gratuity calculation India 2026 formally called the Payment of Gratuity Act of 1972 apply to every workplace that has employed ten or more people at any time in the twelve months. Once a workplace has ten employees the Act remains in force forever even if later the number of employees falls below ten. Factories, mines, plantations, shops and all other workplaces are included in the Act.
Government workers are covered by rules and receive a full tax exemption on gratuity with no limit. The formula for gratuity calculation India 2026 and the tax rules are different for government workers and for sector workers. This article is, about sector workers who are protected by the Payment of Gratuity Act of 1972.
Gratuity eligibility in 2026
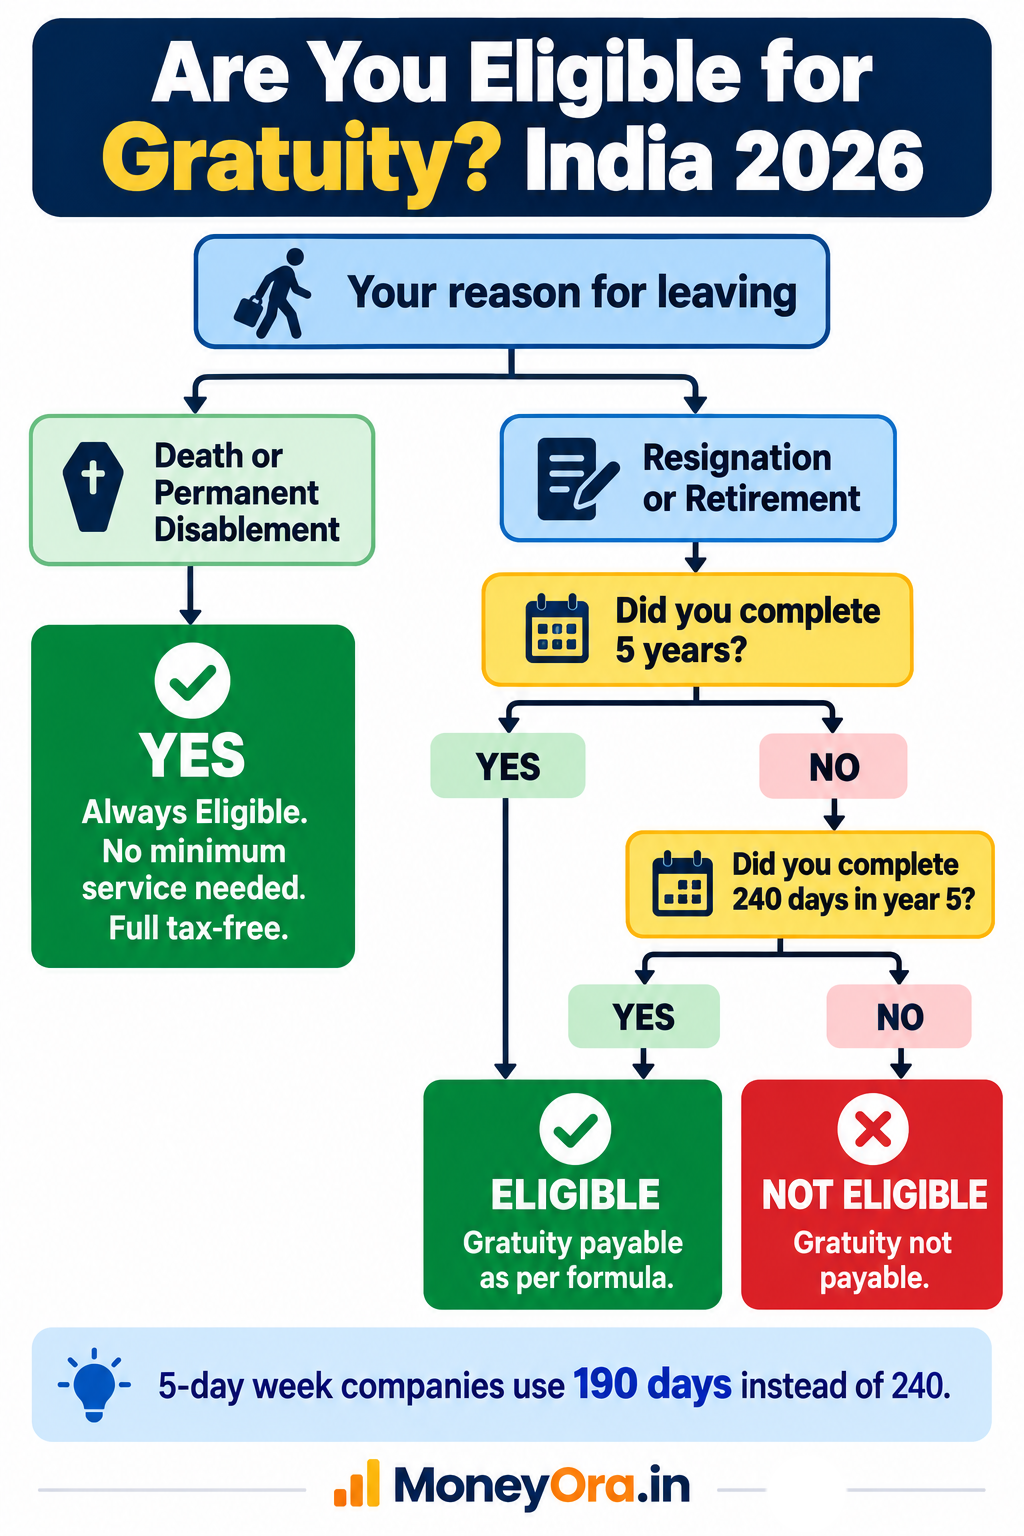
To receive gratuity calculation India 2026 benefits you must meet three conditions. The gratuity calculation India 2026 rules are set by the Payment of Gratuity Act 1972
| Condition | What the law says |
|---|---|
| Service length | 5 years of continuous service (or 4 years plus 240 working days in the 5th year for 6-day week companies) |
| Employer size | The establishment must employ or have employed 10 or more persons |
| Reason for leaving | Resignation or retirement or superannuation or death or permanent disablement |
The 5-year rule in gratuity calculation India 2026 has one important exception for fixed-term employees. Under proposed changes linked to the Code on Social Security 2020 fixed-term contract employees may become eligible after one year of service. As of October 2026 this provision is not yet fully notified as law for all establishments. Check with a labour law advisor for your specific situation.
Death and permanent disablement waive the service requirement entirely. Gratuity is payable immediately regardless of how many months the person worked. The nominee or legal heir receives the full amount.
The 4 year 8 month rule explained in words
This is the most misunderstood rule in gratuity calculation India 2026 and leads to many disputes between employees and employers. Many employees resign at 4 years and 7 months or 4 years and 10 months. Get told they are not eligible. That can be wrong.
Section 2A of the Payment of Gratuity Act 1972 which governs gratuity calculation India 2026 defines service. It says that if an employee works for 240 days in any given year that year is counted as a completed year of service. Multiple High Courts including the Madras High Court in cases and the Bombay High Court have applied this to the 5th year of service and ruled that an employee who completes 4 full years and then works 240 actual days in the 5th year has fulfilled the continuous service requirement and is entitled to gratuity.
The Supreme Court in Surendra Kumar Verma v Central Government Industrial Tribunal (1980 SCC 4 433) confirmed the principle.
What does 240 days mean in practice
For a company with a 6-day week you need 240 actual working days in the 5th year. This is 8 months. For a company with a 5-day working week the threshold drops to 190 days. Leaves taken on paid leave count, toward the 240 days. Unpaid absences do not.
So if you joined on 1 January 2022 and your company works 6 days a week you need to work least 240 days after 1 January 2026 (the start of your 5th year) to qualify. That takes you to August or September 2026 depending on Sundays and public holidays.
Note. This is a judicial interpretation and not all employers accept it without a dispute. If your employer denies gratuity citing the 5-year calendar rule you can escalate to the Controlling Authority as explained in the claim section below. Courts have consistently ruled in the employees favor when the 240-day mark is proven.
The gratuity calculation India 2026 formula
For employees covered under the Payment of Gratuity Act 1972 the formula is
The gratuity calculation India 2026 formula for covered employees is
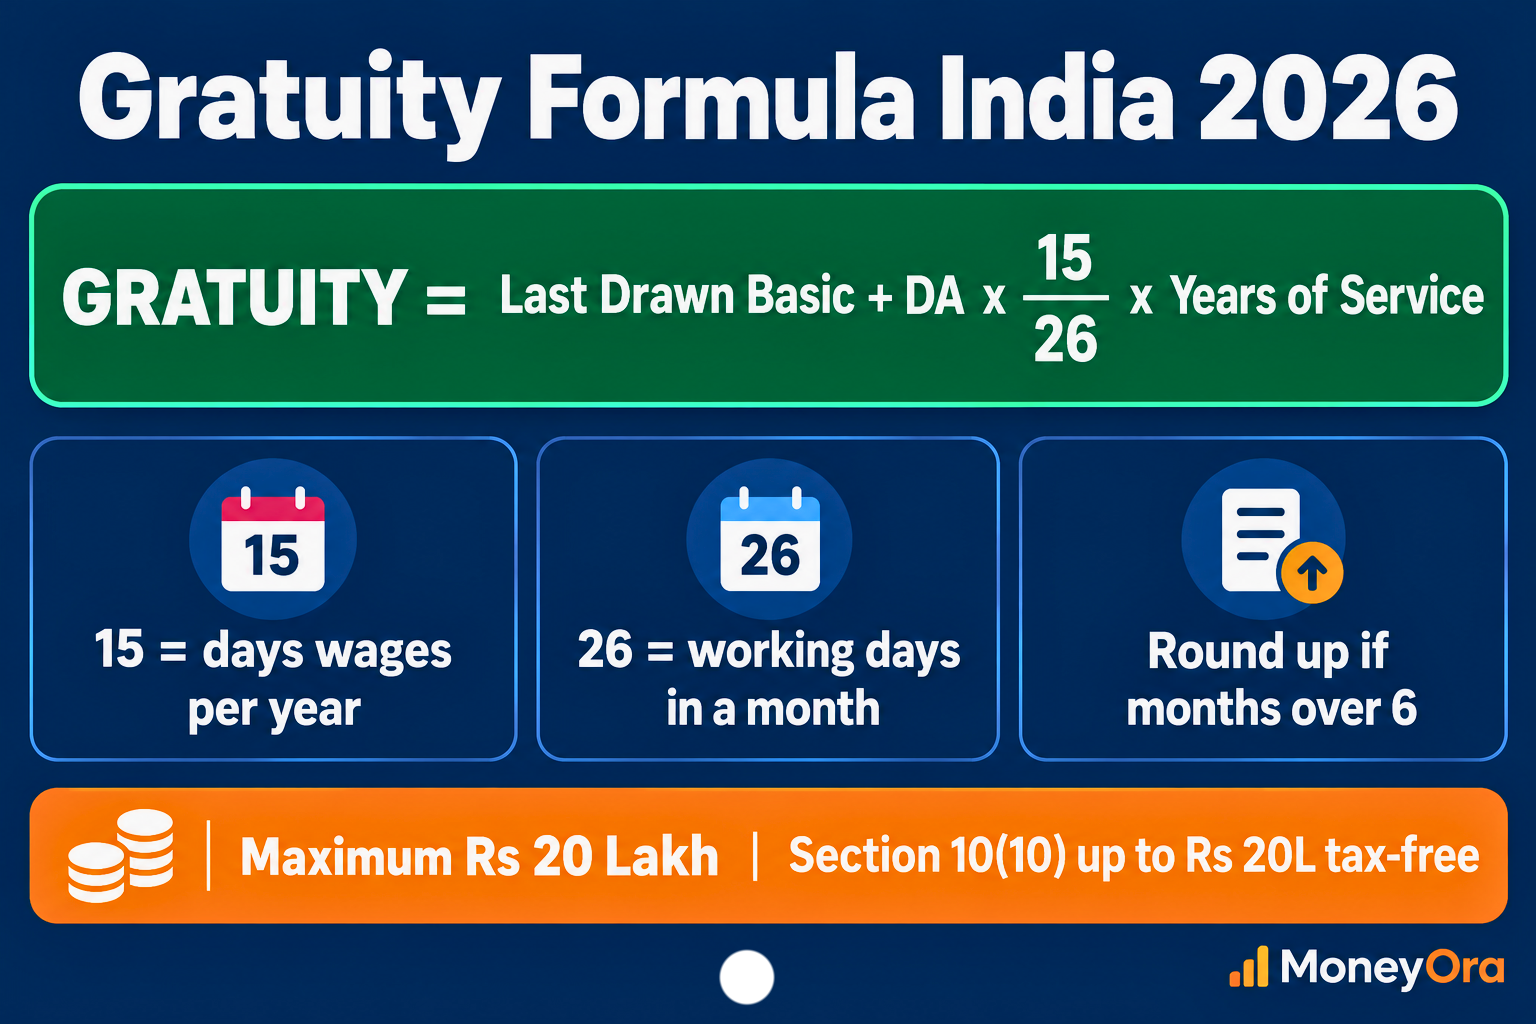
Gratuity = Last Drawn Basic Salary plus DA multiplied by 15 divided by 26 multiplied by Completed Years of Service
Breaking down each part of the gratuity calculation India 2026 formula
| Part of formula | What it means |
|---|---|
| Last drawn basic plus DA | Your monthly basic salary plus dearness allowance on your last working day |
| 15 | 15 days of wages for each completed year of service |
| 26 | A month is assumed to have 26 working days (30 calendar days minus 4 Sundays) |
| Completed years of service | Full years only. If the remaining months exceed 6 they round up to the next full year |
The rounding rule for gratuity calculation India 2026 is clear. If you have worked for 10 years and 4 months the completed service is 10 years. If you have worked for 10 years and 7 months the completed service rounds up to 11 years because 7 months is more than 6 months.
The maximum statutory gratuity amount in the gratuity calculation India 2026 is Rs 20 lakh regardless of what the formula produces above that figure. This ceiling was raised from Rs 10 lakh by the Payment of Gratuity Amendment Act 2018 which came into force on 29 March 2018 (verified at labour.gov.in)
For employees not covered under the Act (rare cases such as small establishments below 10 employees paying gratuity under a contract) the denominator changes from 26 to 30 and the base salary is the average of the last 10 months instead of the last drawn salary
Non-covered formula is Last 10 months average salary multiplied by 15 divided by 30 multiplied by completed years of service
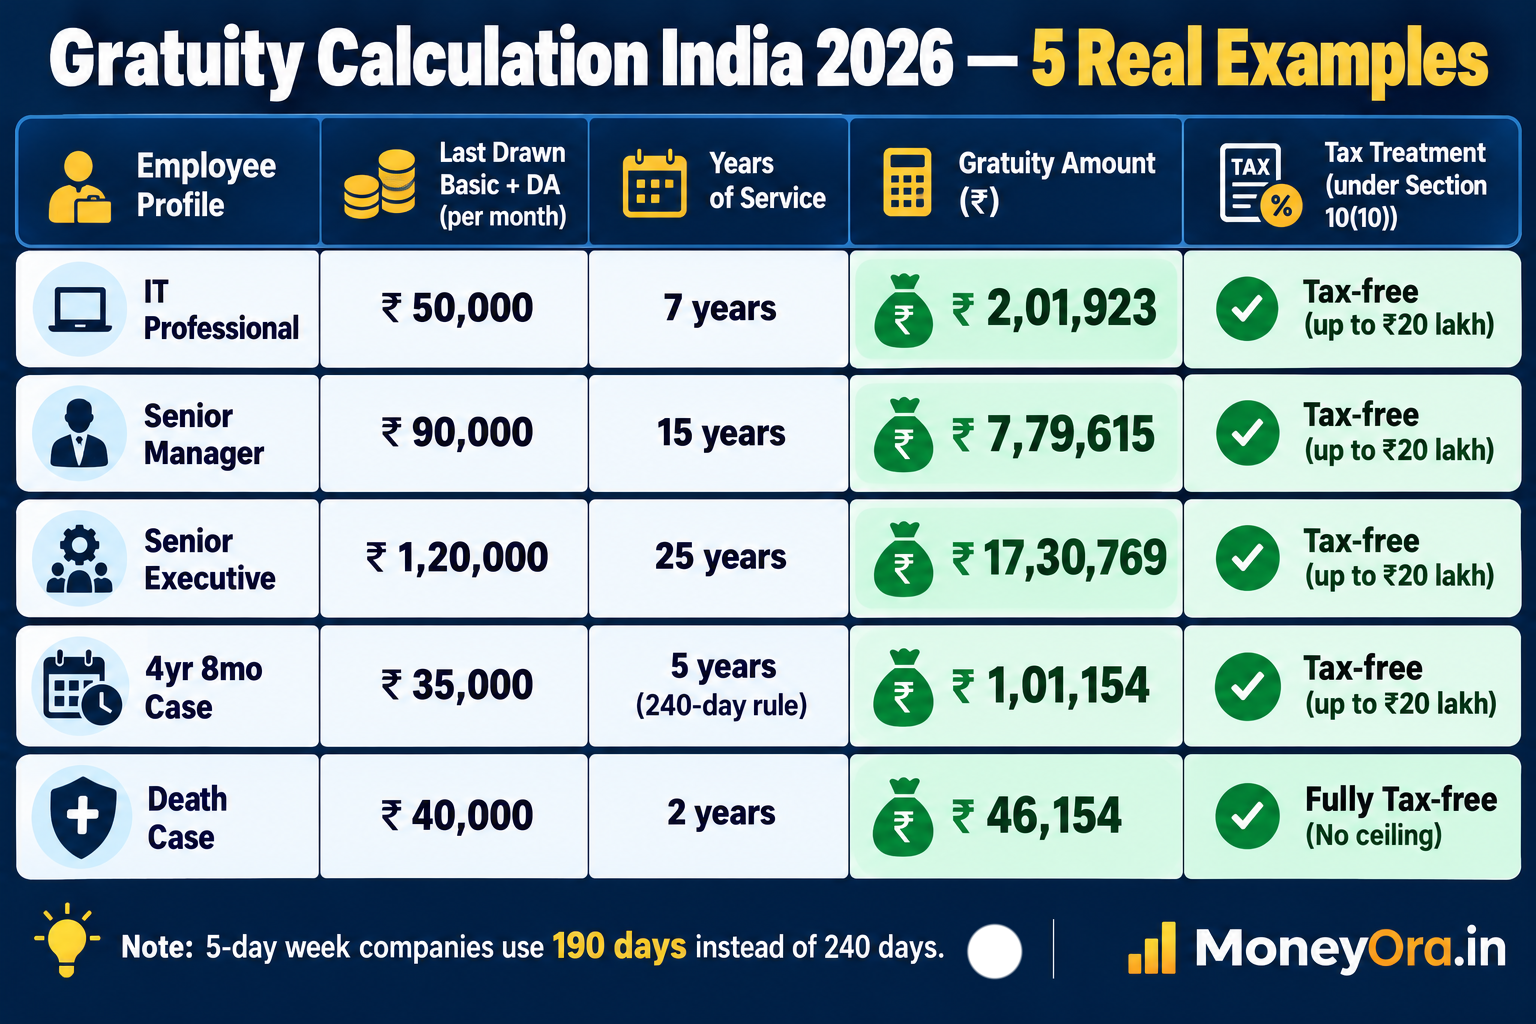
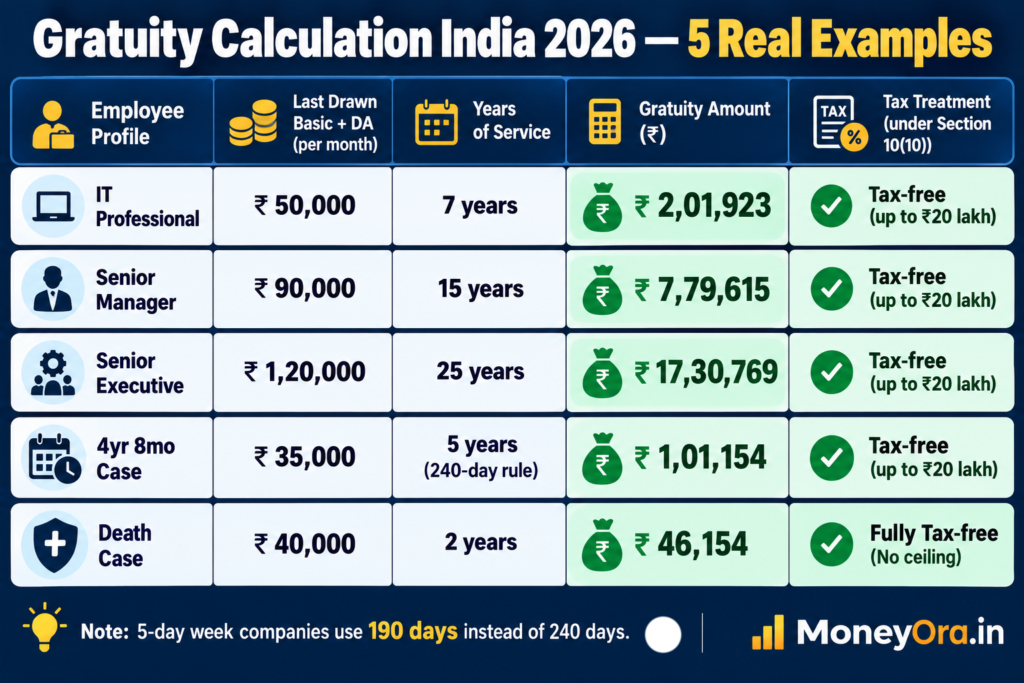
Five worked rupee examples for gratuity calculation India 2026
Every example below uses only verified information. Each gratuity calculation India 2026 example uses the 15/26 formula confirmed under the Payment of Gratuity Act 1972. The gratuity calculation India 2026 uses the standard 15/26 formula confirmed under the Payment of Gratuity Act 1972.
Example 1 – Mid-level IT professional after 7 years
Basic salary plus DA is Rs 50000 per month
Completed years of service is 7
Gratuity = 50000 multiplied by 15 divided by 26 multiplied by 7
Gratuity = 50000 multiplied by 0.5769 multiplied by 7
Gratuity = Rs 2 lakh 1 thousand 923
This amount is below Rs 20 lakh so it is fully tax-free under Section 10(10)(ii)
Example 2 – Senior manager after 15 years
Basic salary plus DA is Rs 90000 per month
Completed years of service is 15
Gratuity = 90000 multiplied by 15 divided by 26 multiplied by 15
Gratuity = Rs 7 lakh 79 thousand 615
Fully tax-free as it is below Rs 20 lakh
Example 3 – Senior executive with 25 years hitting the Rs 20 lakh cap
Basic salary plus DA is Rs 1 lakh 20 thousand per month
Completed years of service is 25
Gratuity formula gives 1 lakh 20 thousand multiplied by 15 divided by 26 multiplied by 25 = Rs 17 lakh 30 thousand 769
Gratuity = Rs 17 lakh 30 thousand 769 (below cap so fully tax-free)
Example 4 – The 4-year 8-month case (6-day week company)
Basic salary plus DA is Rs 35000 per month
Service is 4 years and 8 months at a 6-day week company where the employee worked 240 days in the 5th year
Eligibility is confirmed under the High Court 240-day interpretation
Completed service for calculation is 5 years (since 8 months rounds up)
Gratuity = 35000 multiplied by 15 divided by 26 multiplied by 5
Gratuity = Rs 1 lakh 1 thousand 154
Example 5 – Death case with only 2 years of service
Basic salary plus DA is Rs 40000 per month
Actual service is 2 years 3 months (minimum service rule waived)
Completed service for calculation is 2 years
Gratuity = 40000 multiplied by 15 divided by 26 multiplied by 2
Gratuity = Rs 46 thousand 154
Tax treatment – Completely tax-free in the nominee’s hands regardless of the Rs 20 lakh limit
What counts as salary for gratuity calculation India 2026 and what is excluded
This is where most employees and many HR teams go wrong. The gratuity calculation India 2026 uses a specific definition of wages set out in the Payment of Gratuity Act
| Included in gratuity wage base | Excluded from gratuity wage base |
|---|---|
| Basic salary | HRA or house rent allowance |
| Dearness allowance (DA) | LTA or leave travel allowance |
| Variable DA (where explicitly part of basic pay structure) | Medical allowance |
| Special allowance | |
| Conveyance allowance | |
| Incentives and performance bonuses | |
| PF employer contribution | |
| Gratuity provision in CTC |
A major change linked to the Code on Social Security is the 50% wage rule. Under this rule if the components excluded from wages (such as HRA and allowances) exceed 50% of the total CTC the excess is added back to the wage definition for calculating gratuity and EPF. This effectively raises the gratuity base for employees in high-allowance CTC structures. As of October 2026 the full Code on Social Security is not yet notified for all establishments so verify the applicable rule for your employer.
The practical implication is this – if your monthly gross is Rs 1 lakh and your basic is only Rs 25000 your gratuity is calculated on Rs 25000 not Rs 1 lakh. Employers structure salaries this way deliberately to reduce gratuity liability. The 50% wage rule is designed to close this gap.
Gratuity tax exemption rules relevant to gratuity calculation India 2026
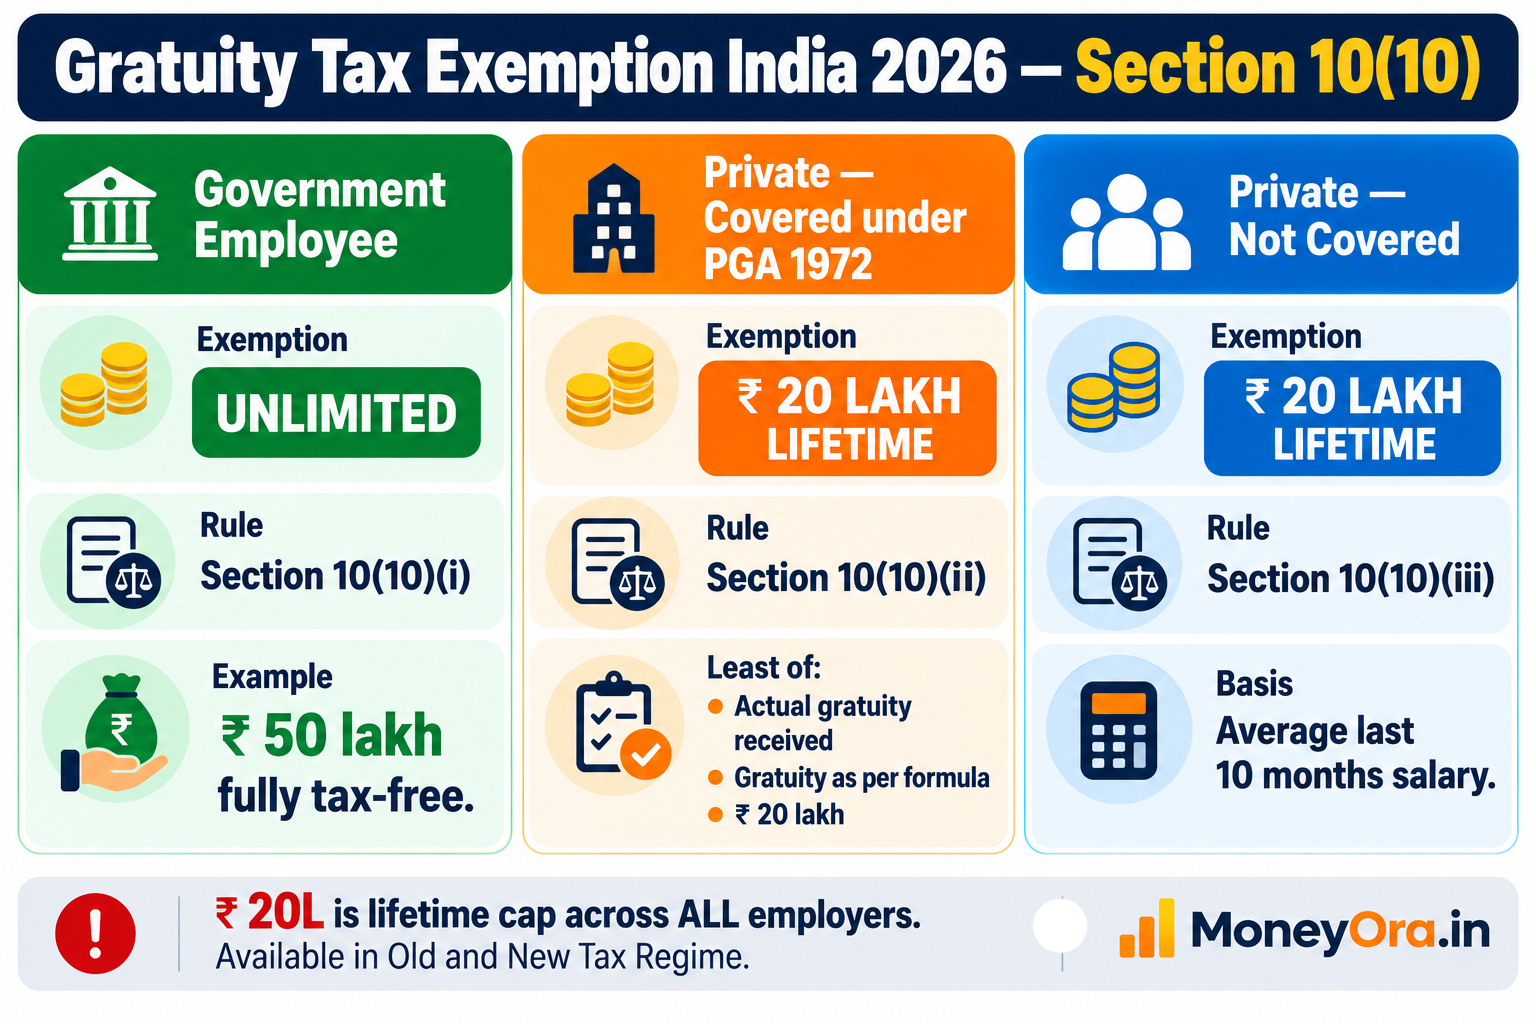
Under Section 10(10) of the Income Tax Act 1961 gratuity enjoys tax exemption. The rules differ by employee category verified at incometaxindia.gov.in
Government employees and gratuity calculation India 2026 tax exemption
The gratuity calculation India 2026 amount is exempt from income tax under Section 10(10)(i). There is no limit. A government employee receiving Rs 50 lakh as gratuity pays zero income tax on it.
Private sector employees and the gratuity calculation India 2026 ceiling
The exempt amount for gratuity calculation India 2026 is the least of these three.
- Actual gratuity received
- Gratuity calculated using the formula (Last Drawn Basic plus DA multiplied by 15 divided by 26 multiplied by completed years)
- Rs 20 lakh (lifetime ceiling)
The Rs 20 lakh is a lifetime ceiling, not a per-employer ceiling. If you received Rs 8 lakh as tax‑free gratuity calculation India 2026 from your employer and then receive Rs 15 lakh from your second employer you can only claim Rs 12 lakh as exempt from the second payment because Rs 8 lakh was already used from the Rs 20 lakh lifetime pool.
Private sector employees not covered under the Act. Gratuity calculation India 2026 formula
The exempt amount is the least of three amounts under Section 10(10)(iii).
- Actual gratuity received
- Half of the salary of the last 10 months multiplied by completed years of service
- Rs 20 lakh (same lifetime ceiling)
Key point for 2026. This exemption applies under both the old tax regime and the new tax regime. Switching to the regime does not reduce your gratuity calculation India 2026 exemption.
Note for FY 2026 to 2027: the Income Tax Act 2025 renumbers the gratuity exemption to Section 19 but the substance and limits remain unchanged per verified information, from income tax sources.
Common mistakes employees and HR teams make in gratuity calculation India 2026
These are the most expensive errors in gratuity calculation India 2026. Avoid them to get the right amount.
- Calculating on gross salary instead of Basic plus DA – this overstates the payout and creates compliance risk for employers
- Denying gratuity at 4 years and 8 months when the employee has completed 240 working days in the 5th year
- Using 30 as the denominator instead of 26 for establishments covered under the Act
- Not rounding up when the remaining months exceed 6
- Counting only calendar years instead of continuous service as defined under Section 2A
- Forgetting the Rs 20 lakh lifetime ceiling and giving the employee a full exemption on a second gratuity when the first has already consumed part of the limit
- Structuring CTC so that basic salary is below 50% of CTC – this reduces gratuity now but may create compliance issues when the wage code is notified
How to claim gratuity step by step after your gratuity calculation India 2026
The claim process for gratuity calculation India 2026 follows a defined legal sequence under the Payment of Gratuity Central Rules 1972. Use this gratuity calculation India 2026 guide as a checklist under the Payment of Gratuity Central Rules 1972
Step 1 – Submit Form I to your employer within 30 days of the date gratuity becomes payable. You can also submit Form I up to 30 days before your last day (before retirement) to speed up processing. Send it by registered post and keep the acknowledgment.
Step 2 – The employer must pay the gratuity within 30 days of receiving Form I. If the employer agrees the amount they issue Form L specifying the amount and payment date. Most payments are now made via NEFT or RTGS directly to your bank account.
Step 3 – If the employer disputes the amount or rejects the claim they must issue Form M with reasons within 30 days. Read Form M carefully as it sets out what the employer is contesting.
Step 4 – If you do not agree with Form M or if the employer does not respond at all file Form N with the Controlling Authority for your area. The Controlling Authority is usually the Assistant Labour Commissioner in your city. File Form N within 90 days of the due date for payment or within 90 days of receiving Form M.
Step 5 – The Controlling Authority hears both sides and can issue directions to the employer to pay. The employer’s failure to comply with a direction is recoverable as land revenue (meaning the government can enforce it like a tax debt). Wilful non-payment is also a criminal offence under Section 9 of the Act carrying imprisonment of up to 2 years and a fine.
Documents to keep ready when submitting your gratuity calculation India 2026 claim
- Offer letter or appointment letter showing your date of joining
- Latest salary slip showing Basic plus DA
- Resignation acceptance letter or relieving letter
- Bank account details for NEFT payment
- Form F (nomination form) acknowledgment if you filed one
You can use the free gratuity calculator on MoneyOra to check the amount you are entitled to before submitting Form I so you can verify if the employer’s calculation matches
What to do if your employer refuses to pay after your gratuity calculation India 2026
If your gratuity claim based on your gratuity calculation India 2026 is denied or delayed
- Send a written reminder by registered post citing Section 7 of the Payment of Gratuity Act 1972 and referencing your gratuity calculation India 2026 entitlement and asking for payment or Form M within 30 days
- File Form N with the local Controlling Authority (Assistant Labour Commissioner) if there is no response or you disagree with Form M
- Claim interest at 10 percent per year on the delayed amount from the due date under Section 7(3A)
- File an RTI with the Labour Commissioner’s office to get the status of your Form N if the case stalls
- Legal representation is not required at the Controlling Authority stage but is helpful if the employer contests aggressively
For further disputes about gratuity calculation India 2026 amounts the Ministry of Labour and Employment maintains the Sampark portal where you can track certain labour grievances online. The EPFO and labour department also maintain state-level SAMADHAN portals for hybrid hearings in some states.
You can also check your EPF balance and service record to corroborate your service dates using the free EPF calculator on MoneyOra which also shows how gratuity and EPF work together as retirement benefits
Gratuity calculation India 2026 and your overall retirement planning
Gratuity calculation India 2026 is one piece of your exit or retirement benefit. The other two are EPF and leave encashment. The table below shows how they compare
| Benefit | Who contributes | Tax-free limit | Basis |
|---|---|---|---|
| Gratuity | Employer only | Rs 20 lakh lifetime | Last drawn basic plus DA multiplied by tenure |
| EPF | Both employer and employee at 12 percent each | Fully tax-free after 5 years of continuous contribution | Monthly contribution compounded at EPF interest rate |
| Leave encashment | Employer | Rs 25 lakh lifetime for non-government employees | Per-day basic pay multiplied by earned leave balance |
Your gratuity calculation India 2026 amount is only one part of your total exit benefit. EPF typically grows much larger than gratuity over a long career because EPF compounds monthly while gratuity grows linearly on last drawn salary. A person who works for 25 years at the same employer may find their EPF corpus is 5 to 8 times their gratuity amount purely because of compound interest on decades of monthly contributions
Use the income tax calculator on MoneyOra to estimate how much of your gratuity receipt will be taxable after applying the Section 10(10) exemption in your specific situation
This article is educational and does not constitute personalised legal or financial advice. Gratuity rules may change and individual situations vary. Verify all figures and eligibility with your employer’s HR and with a qualified labour law advisor or chartered accountant before acting. For official information refer to the Payment of Gratuity Act 1972 available at labour.gov.in and to the Income Tax Act 1961 at incometaxindia.gov.in
Frequently asked questions on gratuity calculation India 2026
What is the formula for gratuity calculation India 2026?
The formula for gratuity calculation India 2026 for sector employees covered under the Payment of Gratuity Act 1972 is Last Drawn Basic plus DA multiplied by 15 divided by 26 multiplied by completed years of service. For a salary of Rs 40000 and 10 years of service this gives Rs 2 lakh 30 thousand 769
Can I get gratuity after 4 years and 8 months?
Yes if your company works 6 days a week. You completed 240 actual working days in your 5th year. Multiple High Courts have held this counts as 5 completed years under Section 2A of the Payment of Gratuity Act 1972. For 5-day week companies the threshold is 190 days
Is gratuity taxable in India in 2026?
Your gratuity calculation India 2026 result is tax-free up to Rs 20 lakh lifetime for sector employees under Section 10(10) of the Income Tax Act 1961. Government employees get exemption with no upper limit. Any gratuity above the exemption is taxed at your slab rate. The exemption applies under both new tax regimes
What is gratuity calculated on. Basic or gross?
Gratuity is calculated on Basic Salary plus Dearness Allowance. HRA and LTA and medical allowance and other components are excluded. Calculating on salary is one of the most common HR errors in gratuity calculation India 2026
What is the maximum gratuity amount in 2026?
The statutory ceiling is Rs 20 lakh for employees covered under the Payment of Gratuity Act 1972 as raised by the 2018 amendment. An employer may pay more. The tax exemption applies only up to Rs 20 lakh
How do I claim gratuity?
Submit Form I to your employer within 30 days of your working day. The employer must pay within 30 days. Issue Form L or Form M. If there is a dispute file Form N with the Controlling Authority (Assistant Labour Commissioner) for your area
What happens if my employer does not pay gratuity?
You are entitled to 10 percent interest per year on the delayed amount from the date under Section 7(3A) of the Payment of Gratuity Act 1972. File Form N with the Controlling Authority and use the SAMADHAN portal in your state if available
Is gratuity payable on death before 5 years?
Yes. Death and permanent disablement waive the 5-year minimum service rule. Gratuity is payable immediately. The amount received by the nominee is completely tax-free with no Rs 20 lakh ceiling applied
Use the free gratuity calculator, on MoneyOra to get your exact entitlement in seconds. For a picture of your retirement benefits check the EPF calculator and the SIP calculator as well